
A decade ago, the average American family might have viewed a luxury trip to Maui or a week-long excursion through the Italian countryside as a “someday” goal—something reserved for a significant anniversary or a windfall. Today, the sticker shock of travel is even more pronounced. Airfare prices fluctuate wildly; hotel rates in major cities frequently exceed $300 per night, and “resort fees” eat away at your dining budget before you even land. However, you do not need a six-figure income to offset these costs. By strategically leveraging travel credit card rewards, you can strip $2,000 or more off your travel expenses without changing your organic spending habits.
This approach, often called travel hacking for beginners, essentially turns your everyday bills—groceries, utilities, and gas—into a dedicated travel fund. This guide details exactly how to navigate the 2025 travel landscape, earn the right points, and redeem them for maximum value. You will learn how to turn a single credit card signup bonus into a round-trip international flight or a week of free lodging, effectively making your dream vacation a line item you have already paid for through your normal life.
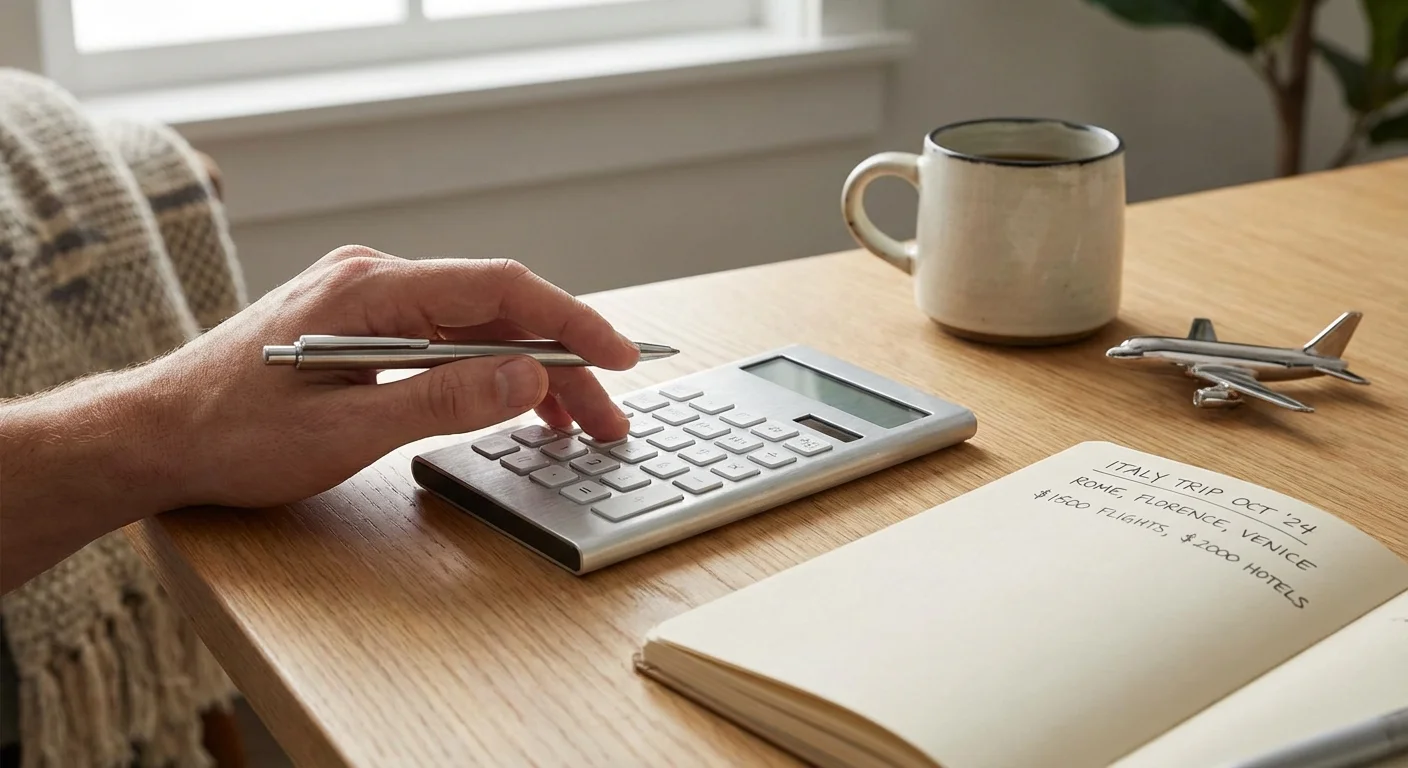
The Math Behind the $2,000 Savings
To save $2,000, you must understand the “valuation” of credit card points. Not all points are created equal. A point worth 0.5 cents toward a toaster in a rewards catalog might be worth 2.1 cents when transferred to an airline partner for a business-class seat or a high-end hotel stay. Budget travel 2025 requires a focus on these high-value redemptions.
Consider a typical “Big Win” scenario using a standard travel credit card guide strategy:
| Expense Category | Retail Cost | Points/Miles Required | Net Cash Savings |
|---|---|---|---|
| Round-trip Flights (2 people) | $1,200 | 60,000 Miles | $1,200 |
| 4 Nights at a Mid-Tier Hotel | $900 | 45,000 Points | $900 |
| Total | $2,100 | 105,000 Points | $2,100 |
Earning 105,000 points might sound like an insurmountable task, but most premium travel cards offer introductory bonuses ranging from 60,000 to 100,000 points just for meeting a minimum spending requirement in the first three months. If you and a partner each open one card, you could easily clear 150,000 to 200,000 points—more than enough to cover a $2,000 vacation discount.
Step 1: Audit Your Credit and Financial Health
Before you apply for any new cards, you must ensure your financial foundation is solid. Credit card rewards are a tool for the disciplined. If you carry a balance and pay interest, the interest charges will quickly outweigh the value of any points you earn. The Consumer Financial Protection Bureau (CFPB) emphasizes that your credit score is the primary gatekeeper to these premium offers. Most top-tier travel cards require a “Good” to “Excellent” credit score, typically 700 or higher.
Check your credit report for errors and ensure your debt-to-income ratio is manageable. If you have high-interest credit card debt, prioritize paying that off before attempting to earn travel rewards. As personal finance expert Suze Orman often says:
“Credit cards are not a way to live beyond your means. They are a tool to manage your means.” — Suze Orman, Personal Finance Author and Expert
If your score is currently in the 600s, focus on six months of on-time payments and reducing your credit utilization. Once you cross the 720 threshold, the most lucrative “welcome offers” become available to you.
Step 2: Choose Your Currency Wisely
One of the biggest mistakes beginners make is earning “trapped” points. For example, if you earn 50,000 points on a specific airline’s card, you can only use those points with that airline or its limited partners. For maximum flexibility and to reach that $2,000 savings goal, you should focus on “Transferable Points.” These are points earned through programs like Chase Ultimate Rewards, American Express Membership Rewards, or Capital One Miles.
Transferable points are valuable because you can move them to dozens of different airlines and hotels. This flexibility allows you to shop for the best deal. If United Airlines wants 50,000 miles for a flight but British Airways only wants 30,000 for the same route via a partner, you can move your points to British Airways and save the difference.
Flexible Points vs. Co-Branded Cards
- Flexible Point Cards: Best for those who want the lowest price regardless of the airline. Examples include the Chase Sapphire Preferred or the Amex Gold.
- Co-Branded Cards: Best for loyalists who always fly one airline or stay at one hotel chain. Examples include Delta SkyMiles cards or Marriott Bonvoy cards.
- Fixed-Value Cards: These cards allow you to “wipe away” travel purchases at a flat rate (usually 1 cent per point). They are simple but rarely offer the outsized value needed to save $2,000 on a single trip.
Step 3: Master the Sign-Up Bonus (SUB)
The signup bonus is the engine of travel hacking. It is the fastest way to accumulate a massive stash of points. A typical offer might look like this: “Earn 60,000 bonus points after you spend $4,000 on purchases in the first 3 months from account opening.”
To hit these requirements without spending extra money, time your applications around large, planned expenses. Are you about to pay your semi-annual car insurance premium? Do you have a dental procedure scheduled? Is it time for back-to-school shopping? Use the card for these necessary costs to meet the threshold. You can also use services like Plastiq to pay rent or utilities with a credit card, though you should calculate the processing fees to ensure they don’t negate the point value. Detailed guides on managing these requirements can be found on sites like NerdWallet or Bankrate.
Step 4: The Art of the Redemption
Earning points is only half the battle; the real savings happen during redemption. To save $2,000, you must avoid the “Travel Portal Trap.” Most banks have their own travel booking portals (similar to Expedia). While convenient, these portals usually value your points at a fixed rate of 1 to 1.5 cents each.
To unlock massive value, you should transfer your points directly to airline and hotel loyalty programs. This is where you find “sweet spots.” For example, a flight from New York to London might cost $900 in cash or 60,000 points in the portal. However, by transferring those same points to a partner like Virgin Atlantic, you might find the same flight for only 20,000 points plus some taxes. In this scenario, your points are worth significantly more, stretching your “points budget” further.
Similarly, hotel transfers to programs like World of Hyatt often yield high value. Hyatt still uses a “Category” system rather than purely dynamic pricing, meaning a high-end resort in a peak season might still only cost 25,000 points, even if the cash price has spiked to $800 a night. That single redemption saves you $800 instantly.
Common Mistakes to Avoid
While the rewards are significant, the pitfalls can be costly. Avoid these common errors to keep your finances in the black:
- Ignoring Annual Fees: Many top-tier cards charge annual fees ranging from $95 to $695. Ensure the benefits (like airport lounge access, TSA PreCheck credits, or annual hotel nights) outweigh the fee.
- Missing the Minimum Spend Window: If the requirement is $4,000 in 90 days and you spend $3,999, you get zero bonus points. Track your spending religiously.
- Closing Cards Too Early: Closing a card within the first year can lead to the bank “clawing back” your points and may damage your relationship with that lender.
- Overspending for Points: Never buy something you don’t need just to earn rewards. A 2% or 5% return in points never justifies a 100% loss of cash on an unnecessary purchase.
Professional vs. Self-Guided Travel Planning
Depending on your comfort level with technology and your available time, you might wonder if you should do this yourself or hire help.
Scenario 1: The DIY Enthusiast
If you enjoy spreadsheets, reading flight charts, and hunting for deals, the self-guided route is best. You will learn the nuances of airline alliances (like Star Alliance or Oneworld) and maximize every single point. This is the most cost-effective way to save $2,000 because you aren’t paying a consultant.
Scenario 2: The Time-Poor Professional
If you have accumulated 500,000 points but don’t have the time to find “award space” (the specific seats airlines release for points), you might use an award booking service. These professionals charge a flat fee (usually $100-$200) to find the absolute best use of your points. If they save you $2,000 on a flight, the $150 fee is a high-ROI investment.
Scenario 3: The Complex Multi-City Trip
If you are planning a “round-the-world” trip with four stops, the logistics of point transfers and partner bookings become incredibly complex. This is a situation where a professional’s expertise can prevent you from “wasting” points on inefficient routes.
Comparison of Popular Travel Reward Strategies
| Strategy | Difficulty | Potential Savings | Best For |
|---|---|---|---|
| Cash Back “Eraser” | Low | $500 – $800 | Simplicity seekers; domestic travelers. |
| Transfer Partner Mastery | High | $2,000 – $5,000 | International travelers; luxury hotel stays. |
| “Two-Player Mode” (P1 + P2) | Medium | $4,000+ | Couples who can coordinate two sets of card bonuses. |
Leveraging Your Spending for 2025 and Beyond
As we move through 2025, the landscape of credit card points guide strategies continues to evolve. Banks are becoming more selective, and some are introducing “family” rules that limit how many bonuses you can get across a specific card lineup. To stay ahead, you must stay informed. Use resources like Investopedia to understand how changes in interest rates might affect your card’s terms and conditions.
The goal is to move from “spending money” to “funding experiences.” When you pay for your groceries with a card that earns 4x points on dining and 4x on groceries, you aren’t just buying milk; you are buying a fraction of a flight to Tokyo or a night in a Parisian hotel. Over the course of a year, an average household’s $15,000 in grocery and dining spend can transform into 60,000 points—worth roughly $1,200 when redeemed wisely.
Frequently Asked Questions
Does opening multiple credit cards hurt my credit score?
Initially, your score may drop by 5 to 10 points due to a “hard inquiry.” However, in the long run, having more available credit and a lower utilization ratio often increases your score. The key is to never miss a payment and avoid opening too many cards in a very short window.
How long do I have to wait between card applications?
A safe rule of thumb is to wait 3 to 6 months between applications. This shows lenders that you are not “credit hungry” or in financial distress. Some banks, like Chase, have the “5/24 rule,” meaning they will not approve you for a new card if you have opened five or more cards from any issuer in the last 24 months.
Can I use points to pay for my entire trip?
While points can cover flights and hotels, you will still need to pay for taxes, fees, and daily expenses like food and local transport. Expect to pay roughly $5.60 in taxes for a domestic one-way flight and significantly more for international travel. A “free” vacation still requires a small cash buffer.
Building Your Long-Term Travel Strategy
Saving $2,000 on one vacation is a fantastic start, but the true power of travel credit card rewards lies in sustainability. Once you have earned a few bonuses, focus on cards that offer high “multipliers” for your highest spending categories. If you travel for work, ensure you are using a card that earns 3x or 5x points on travel purchases. If you are a homebody who cooks often, prioritize a card with a high grocery multiplier.
Your next step is to look at your calendar for the next 12 months. Where do you want to go? Identify the “cost” in points for that destination today. Once you have a target, select the card that helps you reach that specific goal. By working backward from your destination, you ensure that every dollar you spend is moving you closer to your next departure gate.
This article provides general financial education and information only. Everyone’s financial situation is unique—what works for others may not work for you. For personalized advice, consider consulting a qualified financial professional such as a CFP or CPA.
Last updated: February 2026. Financial regulations and rates change frequently—verify current details with official sources.


Leave a Reply