
Imagine your car making a sudden, grinding noise on your way to work. For many Americans, this sound triggers an immediate physical reaction: a racing heart, a sinking stomach, and a frantic mental calculation of their bank balance. This visceral response illustrates the profound connection between mental health and money. When you live without a financial cushion, every minor inconvenience feels like a potential catastrophe.
According to the 2023 report from the Federal Reserve, nearly 37% of adults would struggle to cover a hypothetical $400 emergency expense using cash or its equivalent. This statistic represents more than just a lack of liquidity; it represents a massive portion of the population living in a state of constant, low-grade fight-or-flight. Establishing an emergency fund does more than pay for new brake pads—it fundamentally rewires your psychological relationship with the world around you.
The Cognitive Load of Financial Insecurity
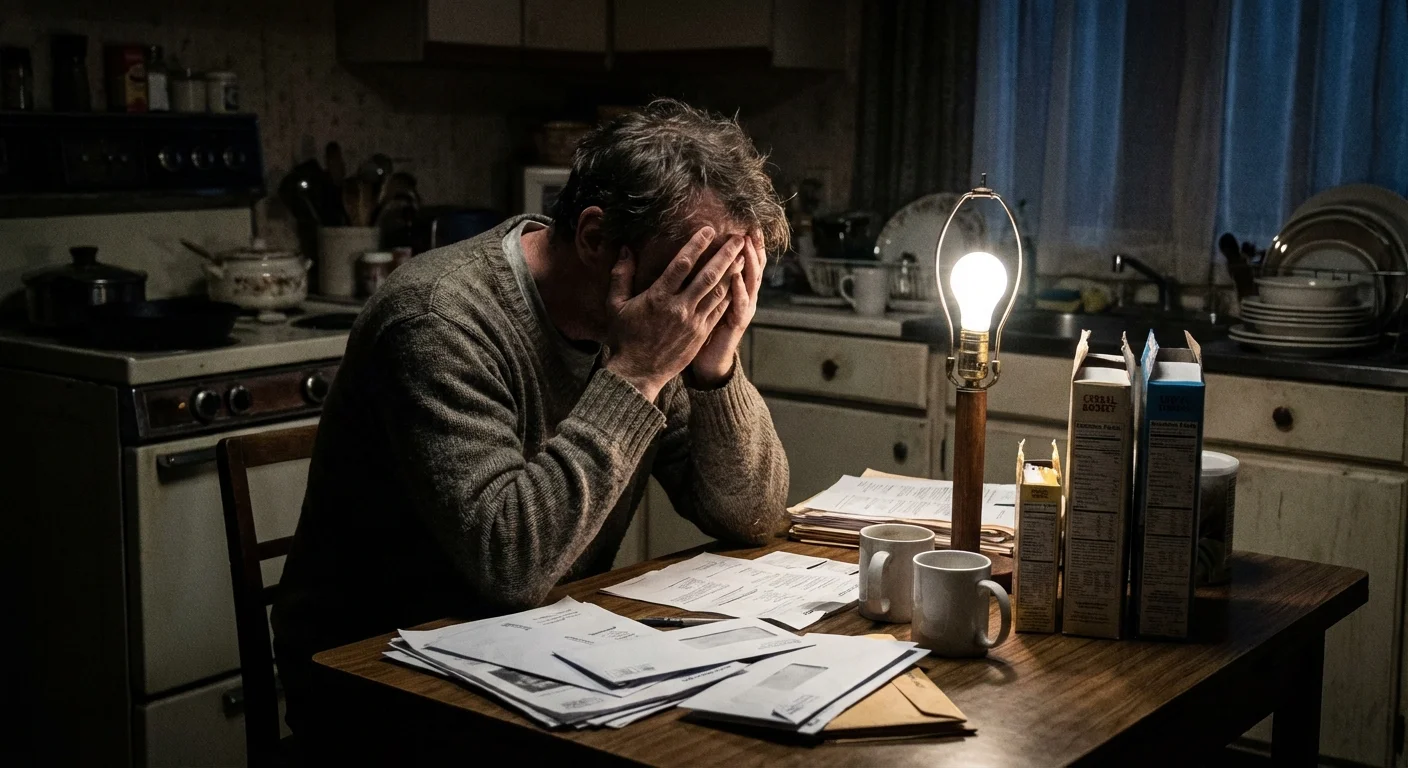
Psychologists and behavioral economists often refer to the concept of “scarcity mindset.” When you lack a vital resource—be it time, food, or money—your brain “tunnels” on the immediate problem. This tunneling effect consumes a massive amount of your cognitive bandwidth, leaving less room for long-term planning, impulse control, and creative problem-solving.
When you lack financial peace of mind, your brain treats a $500 medical bill the same way your ancestors treated a predator in the tall grass. Your body floods with cortisol and adrenaline. While these hormones help you survive a short-term crisis, chronic elevation leads to fatigue, irritability, and poor decision-making. You might find yourself snapping at a spouse or making an impulsive purchase just to feel a momentary sense of control—behaviors that often exacerbate the underlying financial problem.
An emergency fund acts as a psychological circuit breaker. By holding a dedicated pool of cash, you tell your brain that the “predator” is behind a cage. You still see the problem, but you no longer feel the biological urge to panic. This clarity allows you to evaluate your options rationally rather than reacting out of fear.
“The purpose of an emergency fund is to turn a crisis into an inconvenience.” — Dave Ramsey, Personal Finance Author
How a Cash Cushion Breaks the Tunneling Effect
The benefits of emergency fund ownership extend far beyond the ability to pay a bill. Once you bridge the gap between “having nothing” and “having something,” your cognitive capacity literally increases. Research into the “Bandwidth Tax” suggests that individuals preoccupied with financial strain can experience a drop in IQ equivalent to losing a full night of sleep.
When you secure a small starter fund—even just $1,000—you stop the constant mental background noise of “what if?” This creates space for you to:
- Focus on Career Growth: Instead of worrying about how to pay for gas this week, you can concentrate on high-value projects at work that lead to raises.
- Improve Relationships: Money is a leading cause of divorce; removing the immediate threat of insolvency reduces friction between partners.
- Make Better Purchases: Without the pressure of a crisis, you can shop around for the best repair price or wait for a sale rather than taking the first (and often most expensive) option available.
The Peace of Mind Hierarchy
Building an emergency fund is not an all-or-nothing endeavor. You experience psychological relief in stages. You do not need a full six months of expenses to start feeling the benefits. The table below outlines how different levels of savings impact your stress levels and decision-making capacity.
| Savings Level | Psychological Impact | Actionable Capability |
|---|---|---|
| $0 – $500 | High Anxiety; Scarcity Mindset | Reactive; relies on high-interest credit or predatory loans. |
| $1,000 – $2,500 | Reduced Panic; Sense of Control | Can handle most minor car repairs or appliance failures without debt. |
| 1 Month of Expenses | Stability; Ability to Breathe | Can survive a short-term work interruption or a large medical deductible. |
| 3-6 Months of Expenses | Full Autonomy; Future-Oriented | Can leave a toxic job, negotiate from strength, and invest aggressively. |
The “F-You” Money Factor: Financial Autonomy
There is a specific type of psychological freedom that comes with a robust emergency fund, often colloquially referred to as “F-you money.” This isn’t about being rude or reckless; it’s about the power to say “no.”
If you have six months of living expenses sitting in a high-yield savings account, your relationship with your employer changes. You are no longer a hostage to a paycheck. If your workplace becomes toxic, or if you are asked to do something that violates your ethics, you have the financial runway to walk away and find a better fit. This sense of agency is one of the greatest contributors to long-term happiness and mental health.
Without this cushion, you might feel forced to endure mistreatment or stay in a dead-end role because the alternative is immediate financial ruin. The emergency fund provides the leverage you need to advocate for yourself.
Establishing Your Fund Without Overwhelming Your Brain
The thought of saving $10,000 or $20,000 can be paralyzing. To combat this, use behavioral psychology to your advantage. Focus on small, “sticky” habits rather than grand gestures. The Consumer Financial Protection Bureau (CFPB) emphasizes that the act of saving regularly is often more important than the initial amount.
- Automate the Decision: Human willpower is a finite resource. Set up a recurring transfer from your checking account to a separate savings account on every payday. If you never see the money, your brain doesn’t register it as a “loss.”
- Use a Separate Bank: Keep your emergency fund in a different institution than your daily checking. This creates “friction.” By making it slightly harder to access the money, you prevent yourself from spending it on non-emergencies during a moment of weakness.
- Name Your Account: Instead of “Savings,” name the account “Peace of Mind” or “Safety Net.” This psychological labeling reminds you of the money’s purpose when you are tempted to raid it for a vacation.
“Fear is a choice. Financial security is a choice. You must choose to value your future self more than your current impulses.” — Suze Orman, Financial Expert
Pitfalls to Watch For
As you build your fund, your brain may try to sabotage your progress. Watch for these common psychological traps:
- The “Sale” Emergency: You might convince yourself that a 50% discount on a new television is an “emergency” because you’re “saving money.” It isn’t. An emergency is an unplanned, necessary expense.
- Over-Saving: While rare, some people become so addicted to the safety of cash that they refuse to invest for the long term. Once you hit six months of expenses, additional cash should generally be directed toward retirement accounts or debt repayment to combat inflation.
- The Comparison Trap: Do not compare your $500 starter fund to someone else’s $50,000 cushion. The psychological benefit comes from the act of protecting yourself, regardless of the starting point.
Getting Expert Help
Sometimes, psychological barriers or overwhelming debt make it difficult to start an emergency fund on your own. Consider seeking professional guidance in the following scenarios:
- Severe Debt-to-Income Issues: If your fixed expenses exceed your income, a non-profit credit counselor from the National Foundation for Credit Counseling (NFCC) can help you restructure your budget.
- Analysis Paralysis: If you have the money but are terrified to “lock it away” or don’t know where to put it, a Certified Financial Planner (CFP) can provide a neutral, third-party perspective.
- Compulsive Spending: If you find yourself consistently raiding your emergency fund for emotional reasons, a financial therapist can help you address the root causes of your spending habits.
Practical Next Steps
You can start improving your financial psychology today. Do not wait for a pay raise or a tax refund. Open a dedicated high-yield savings account and transfer $25. This small act signals to your brain that you are moving from a state of victimhood to a state of agency.
As that balance grows, pay attention to how you feel. Notice the slight reduction in tension the next time you hear a strange noise or see a new bill. That feeling is the true ROI of an emergency fund. You aren’t just saving money; you are buying back your mental health and your ability to lead a proactive, empowered life.
The information in this guide is meant for educational purposes. Your specific circumstances—including income, debt, tax situation, and goals—may require different approaches. When in doubt, consult a licensed professional.
Last updated: February 2026. Financial regulations and rates change frequently—verify current details with official sources.

Leave a Reply